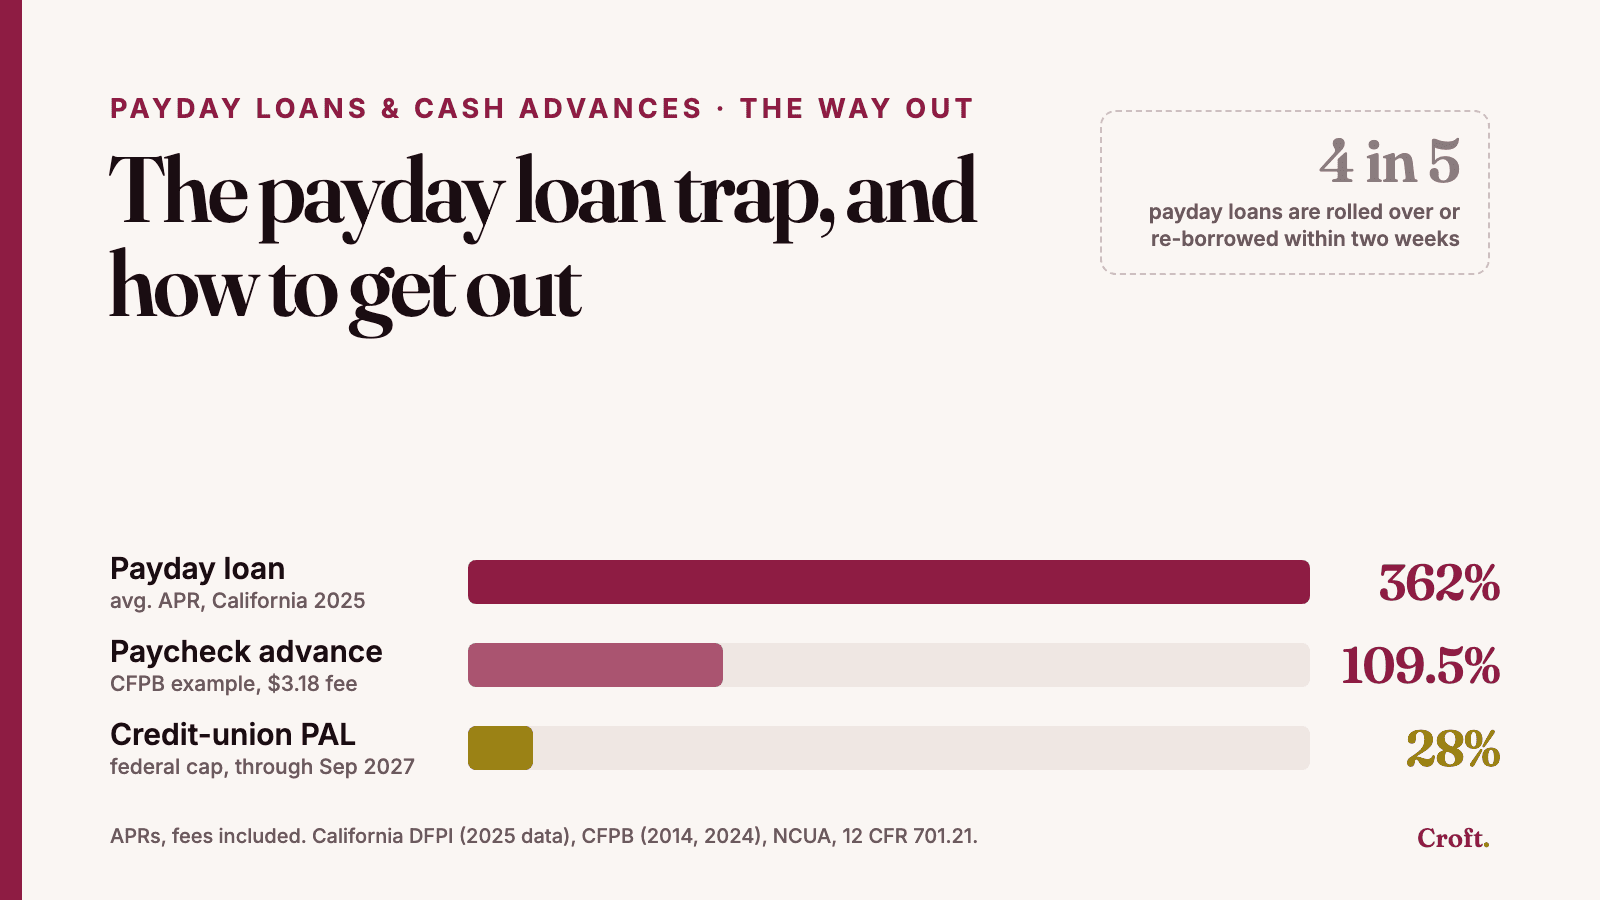
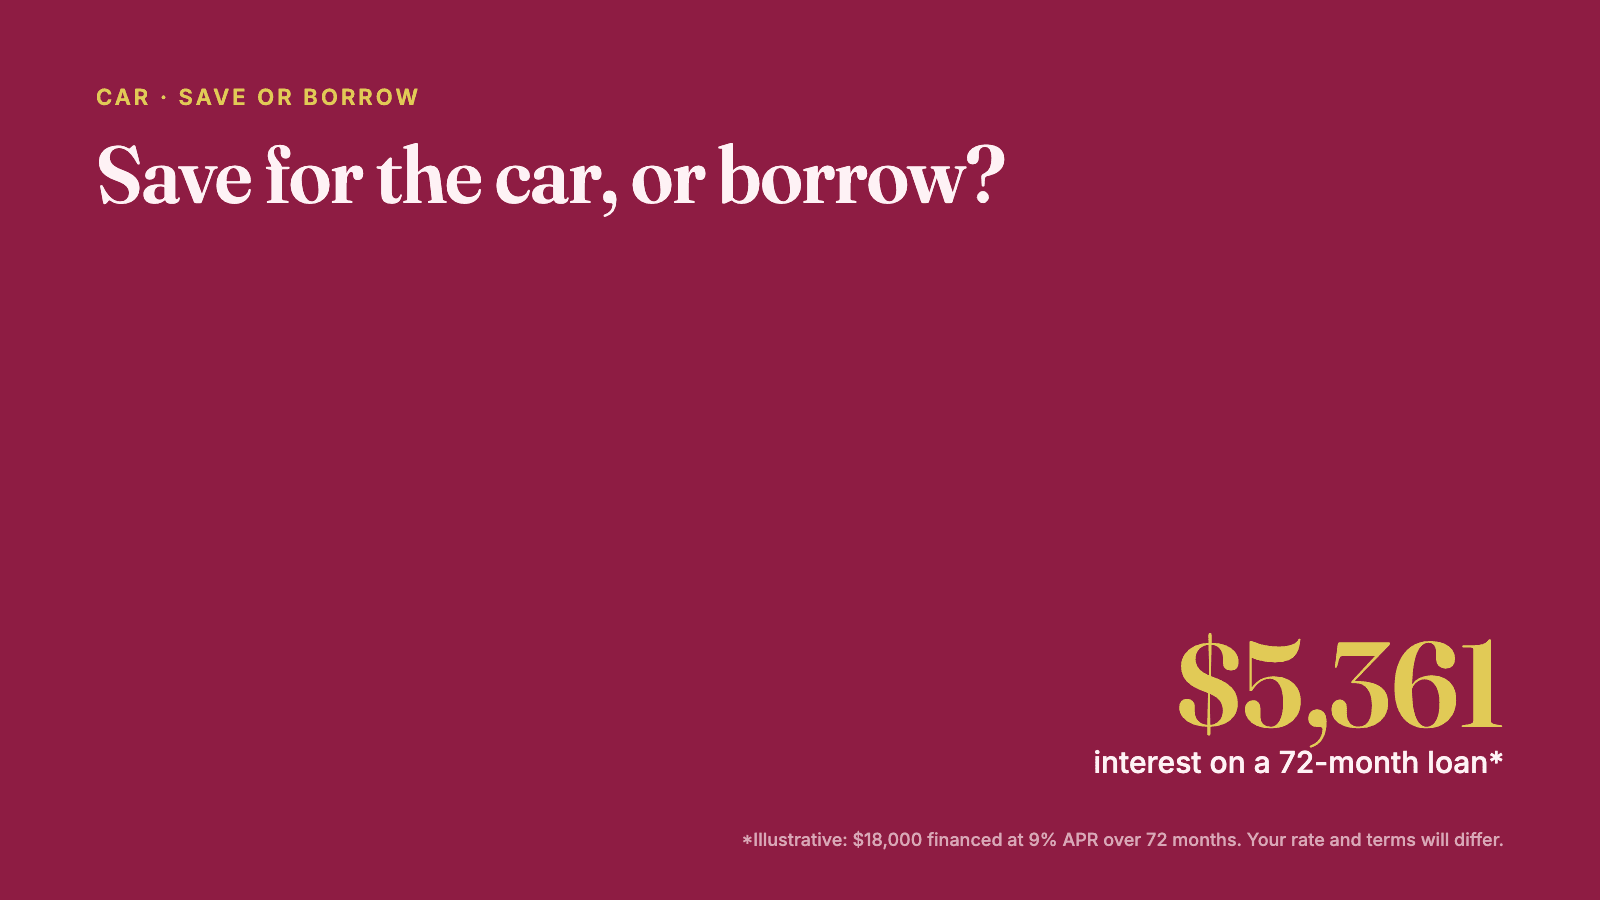A payday loan or cash-advance app gets you to the next paycheck, then takes a big bite out of it, so you borrow again. Here's the math on a $400 loan and a $100 app advance, why it's hard to stop, and the steps that get you out, one loan at a time.
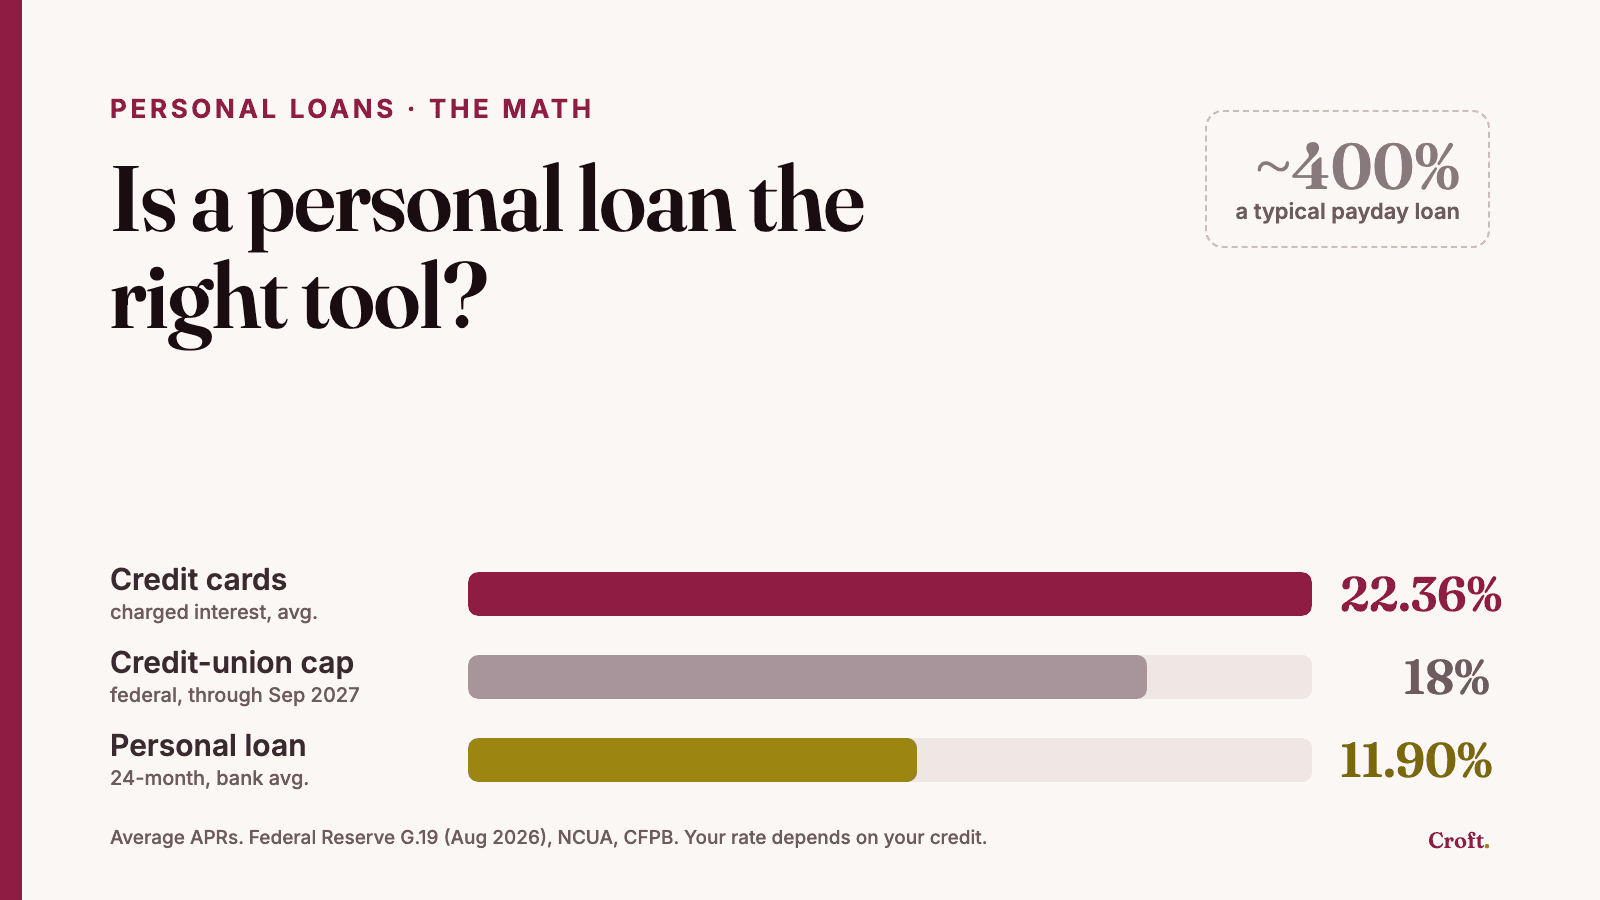
A personal loan can replace expensive, open-ended card debt with a cheaper, fixed payoff. It only works if the payment fits your budget and you don't run the cards back up. Here's how to tell, with the math worked out on a $12,000 example and the alternatives worth checking first.
If your current car can last and you carry card debt, save first: clear the 24% card, then buy with cash or a big down payment. If you need a car now for work, a short, low-APR loan with money down is fine, as long as the payment fits your paycheck.
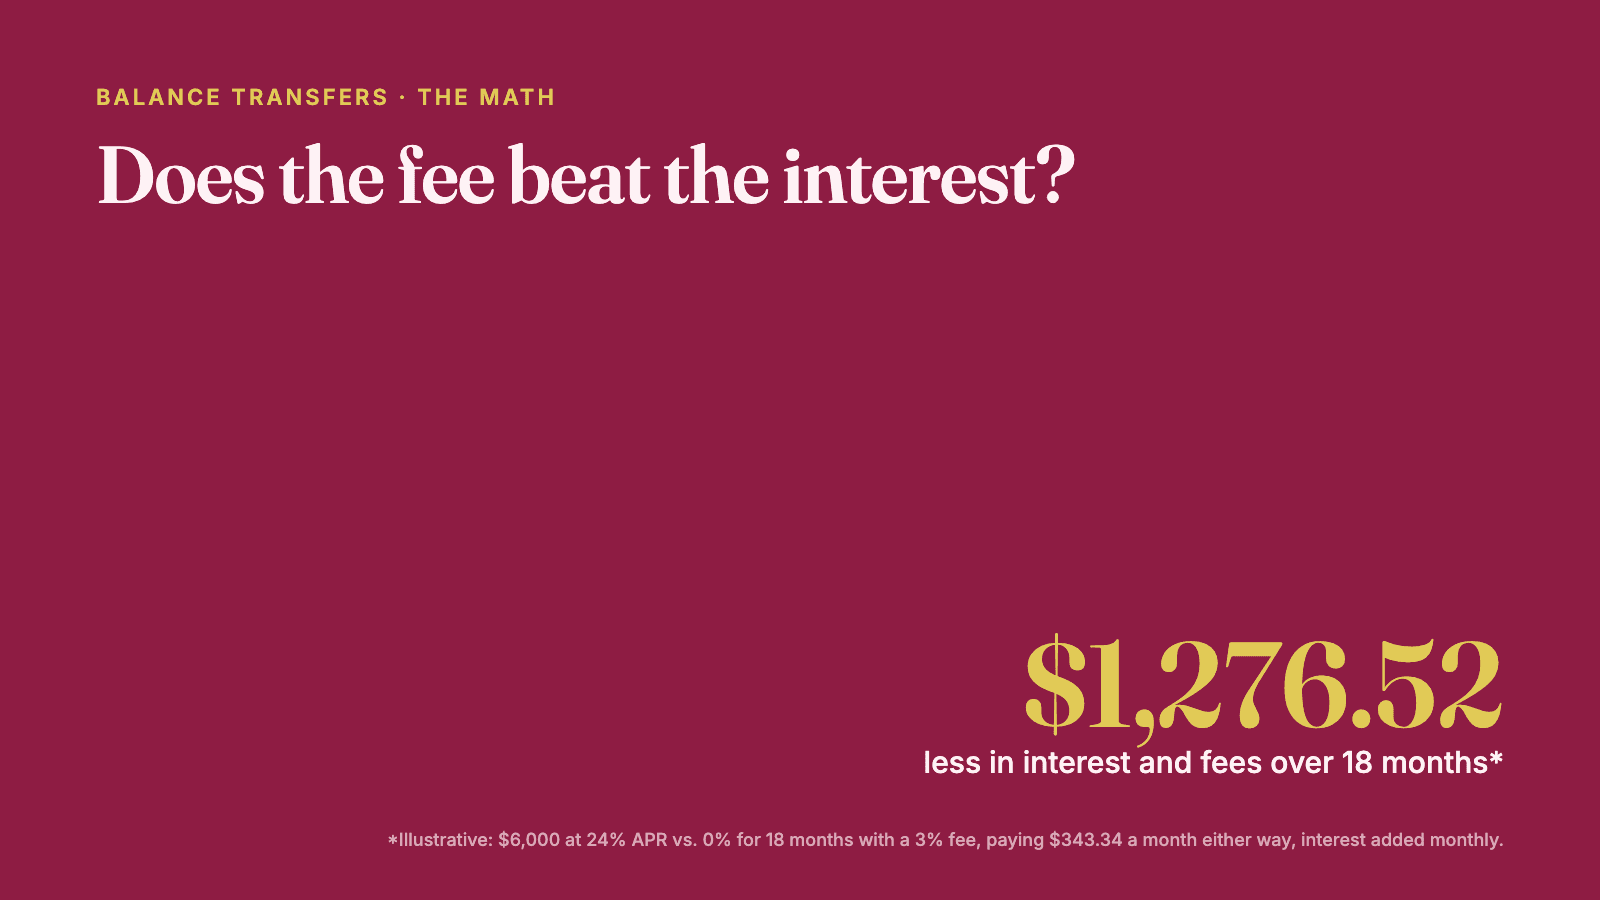
A balance transfer helps when the fee is less than the interest you'd pay, you can clear the balance before the 0% rate ends, and you stop adding charges. Here's the math, with a $6,000 example and a $200-a-month case.
· 7 min read
Free tools
Quick calculators that run in your browser. No sign-up.